ISLAMABAD – (Staff Reporter/Web Desk) – Pakistan IMF $1.21 billion financing is now a step closer after the International Monetary Fund reached a staff-level agreement with Pakistani authorities. The deal still needs approval from the Fund’s Executive Board.
The agreement covers the fourth review of Pakistan’s 37-month Extended Fund Facility (EFF). It also covers the third review of the 28-month Resilience and Sustainability Facility (RSF). The IMF shared the news on Wednesday.
If the board approves, Pakistan will get about $1 billion under the EFF. Another $210 million will come under the RSF. Total payments under both programmes would then reach about $5.7 billion.
An IMF team led by Iva Petrova held talks in Karachi and Islamabad. The meetings ran from September 23 to October 7. They also covered the 2026 Article IV consultation.
The Fund said Pakistan kept its economy stable despite the Middle East conflict. Higher energy prices and supply problems put pressure on the country. Even so, strong policies helped it cope.
Growth reached 4% in the first three quarters of FY26. For the full year, the IMF estimates growth at 3.6%.
Inflation cooled to about 10.3% in September, after peaking in May. Core inflation stayed under control.
The current account was broadly balanced in FY26, helped by strong remittances. Gross foreign exchange reserves rose to about $21.5 billion by the end of September.
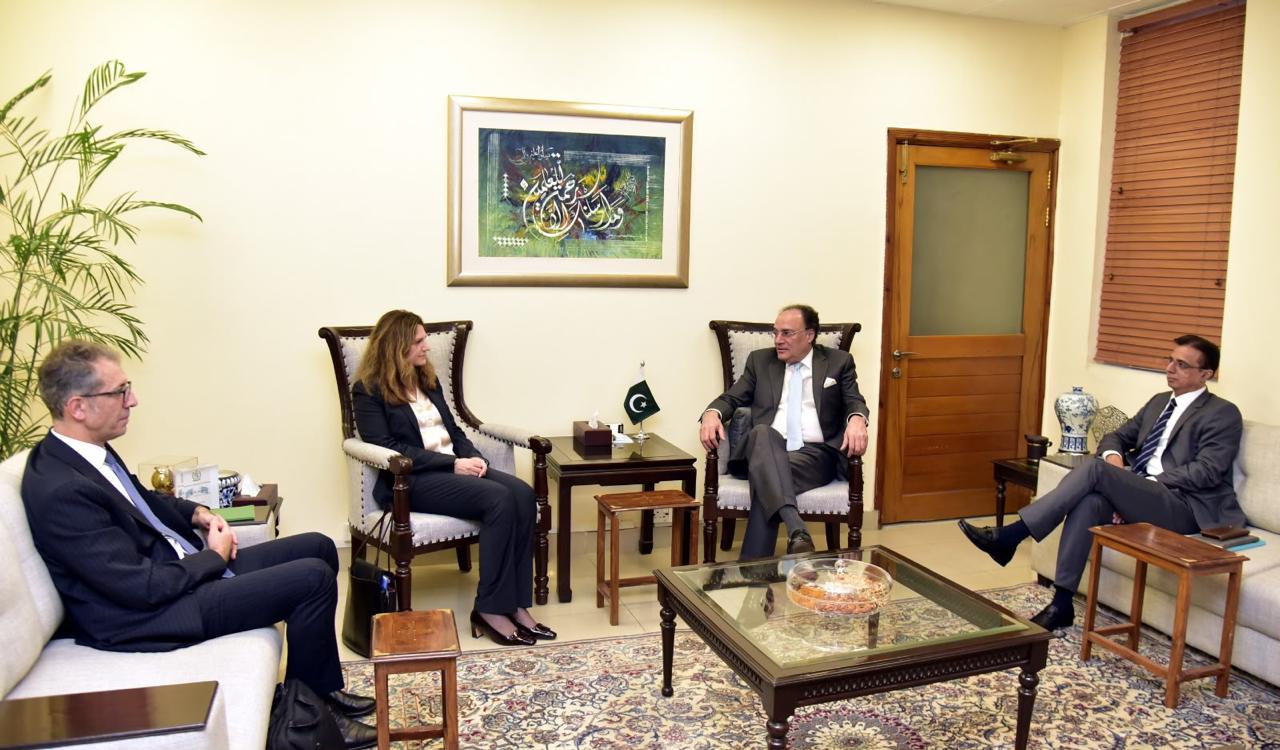
At the conclusion of Fourth Review of Extended Fund Facility (EFF) and Third review of Resilience and Sustainability Facility (RSF), IMF Mission Chief Ms. Iva Petrova held a wrap up session with the Federal Minister for Finance and Revenue, Senator Muhammad Aurangzeb, at the Q Block Pak Secretariat Islamabad. Secretary Finance Mr. Imdad Ulalh Bosal and IMF Resident Representative Mr. Mahir Binici were also present.
— Ministry of Finance, Government of Pakistan (@Financegovpk) October 8, 2026
Still, the IMF warned that risks remain high. It pointed to geopolitical tensions, unstable energy prices, tighter global financial conditions and trade disruptions.
The Fund asked Pakistan to follow its FY27 budget firmly. It set an underlying primary surplus target of 2% of GDP. This would help bring public debt down in a steady way.
It also wants better tax collection. The ideas include risk-based audits, digital invoicing and wider use of third-party data. The IMF hopes Pakistan can build a simpler and fairer tax system.
Public spending needs care too. The Fund urged stronger financial management, better public investment and procurement, and lower debt rollover risks, since financing needs are high.
Health and education spending rose from 2.2% of GDP in FY24 to 2.5% in FY26. The authorities plan to raise it to 2.8% in FY27.
On energy, the IMF called for timely tariff changes and cost cuts. This could stop circular debt from building up again. It also wants better efficiency in the power and gas sectors.
The State Bank of Pakistan should keep a tight policy stance, the Fund said, until inflation returns to its target range. The IMF also backed a flexible exchange rate and more reserve building.
The Article IV review pushed for deeper structural reforms. The goal is to move the economy towards higher-value work and close productivity gaps with similar countries.
The Fund suggested stronger competition and fewer regulatory and trade barriers. It also listed privatisation, better governance of state-owned enterprises and stronger anti-corruption institutions.
It said these steps, along with a fairer tax system and more investment in people and infrastructure, could lift jobs, private investment and exports.
Under the RSF, Pakistan also made progress on climate planning in public investment. It improved its disaster-risk financing as well.
For now, the money is not yet in the bank. Funds can only be released once the IMF Executive Board gives its final approval.
Comments are closed, but trackbacks and pingbacks are open.